...
By Newsweek Editors
0
Share
Newsweek is a Trust Project member
See more of our trusted coverage when you search.Prefer Newsweek on Googleto see more of our trusted coverage when you search.
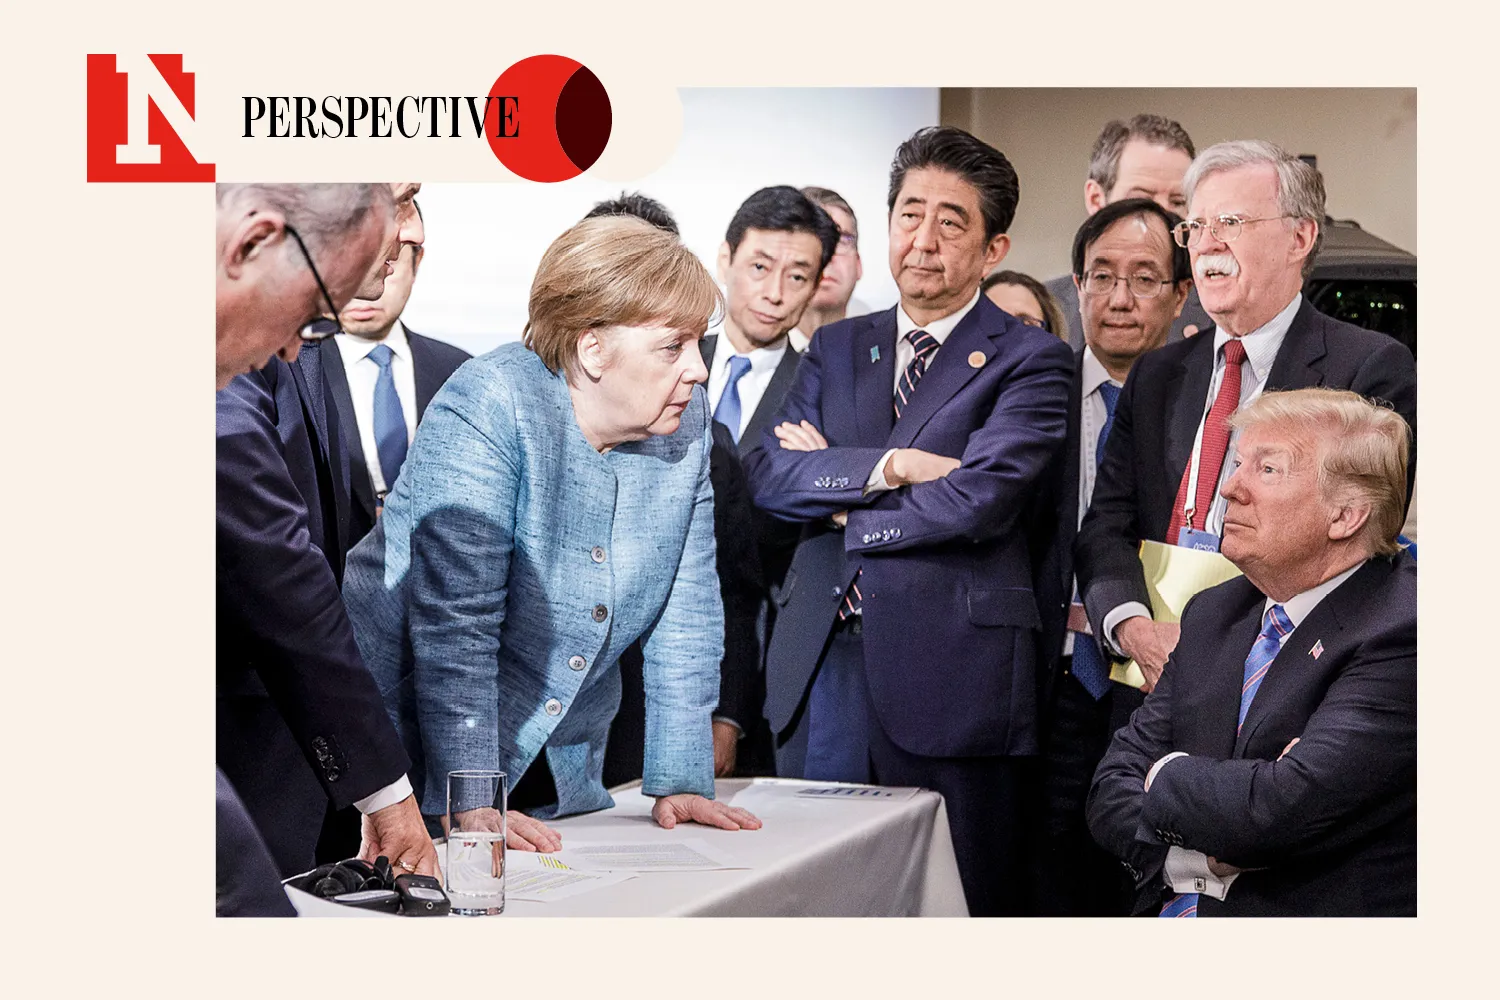
You know the image. June 9, 2018. Charlevoix, Quebec. German government photographer Jesco Denzel caught the scene that came to define Trump-era diplomacy: German Chancellor Angela Merkel leaning over the table, hands planted; French President Emmanuel Macron’s knuckles pressed into the wood; Japanese President Shinzo Abe with his arms folded; U.S. National Security Adviser John Bolton looming behind. And President Donald Trump—seated, arms crossed, chin tilted, apparently immune to the combined exasperation of the democratic world.
The picture went viral because it said what communiqués could not. The leaders of the world’s richest democracies were trying, by sheer posture, to keep an American president inside the system America had built. Hours later, Trump refused to endorse the joint statement from Air Force One, after the summit had already produced a communiqué pledging cooperation on trade, growth, security and democracy.
That was the old strategy: stare him down, appeal to the alliance, hope the table itself would discipline the man sitting at it. Eight years later, the G7 drew a more brutal conclusion. You cannot stare down a president who does not believe in the table. So you add more chairs.
Read More on Analysis
...
The 2026 summit, held from June 15 to 17 in Évian-les-Bains, France, came with the usual alpine scenery, democratic grandeur—and defiance from Trump. “I’m the boss,” he joked as he arrived late for a meeting with fellow world leaders on the final day, before asking photographers who were about to be escorted out, “Would you like to stay for the meeting? It’s OK with me.”
But the guest list was the story. Alongside the core G7 powers—France, the United States, Britain, Germany, Italy, Japan, Canada and the European Union—France brought in India, Brazil, South Korea, Kenya, Egypt, Qatar, Ukraine and the United Arab Emirates. The World Bank, International Monetary Fund, Organization for Economic Cooperation and Development and African Development Bank were also in the room.
This was the first draft of a post-American G7, written while America is still sitting at the table. The French presidency has been admirably discreet about it. Officially, the summit was about geopolitical challenges, Ukraine, the Middle East, international partnerships, balanced economic growth, artificial intelligence, critical minerals and global macroeconomic imbalances. Macron also convened a June 11 video call with the G7 and China, India, Brazil, South Korea and Kenya—extraordinary diplomatic stage management for a club once comfortable pretending it could manage the global economy alone.
For while the G7 still has money, armies and institutions, it no longer has demographic or economic monopoly. One recent estimate puts the G7 at 28.4 percent of global GDP in purchasing-power terms, 9.6 percent of world population and 49.3 percent of global military spending. That is still formidable, but it is also a long way from planetary command.
Nor is Trump incidental to this shift. The Évian summit was originally scheduled to begin on June 14—also the date of Trump’s 80th birthday and a UFC event at the White House. Forbes reported that the summit was moved, while Macron said only that the final dates followed consultation with partners. The choreography is obvious enough. In 2018, the allies tried to bend Trump toward the G7. In 2026, the G7 is bending itself around Trump.
The invitees are the insurance policies. Not all are equal. Some bring legitimacy, some geography, some fuel, some food, some chips, some soldiers, some votes in the Global South. Ranked from least to most important, they reveal what the old rich-country club fears losing most.
No. 8: Qatar, the Gas Valve Insurance Policy
Qatar was the smallest strategic hedge at Évian, but not a trivial one. Its 2026 economy is projected at roughly $217 billion in nominal GDP and $358 billion in purchasing-power terms—tiny beside the U.S., China or India, but attached to one of the world’s most important energy levers. That lever is liquefied natural gas. Qatar accounted for 18.8 percent of global LNG exports in 2024, according to data cited by the International Gas Union, making it one of the three dominant exporters alongside the U.S. and Australia. It also sits inside the diplomacy of the Gulf, Gaza and Iran, which is why Qatar joined Egypt and the UAE for the Middle East session at Évian as G7 leaders called for de-escalation and the reopening of the Strait of Hormuz.
Qatar is not about democratic legitimacy. It is about keeping gas markets, hostage diplomacy and Gulf channels from snapping when Washington becomes erratic. The post-American world will still need fuel—and mediators who can talk to people the G7 would rather not invite to dinner.
No. 7: The UAE, the Oil and Money Insurance Policy
The UAE ranks just above Qatar because it is both a hydrocarbon actor and a capital actor. The IMF’s 2026 estimates put it at about $622 billion in nominal GDP and just over $1 trillion in purchasing-power terms, making it an increasingly useful bridge between Western finance, Gulf energy and non-Western diplomacy.
Energy is the hard edge. The U.S. Energy Information Administration describes the UAE as the seventh-largest total liquid-fuels producer in the world in 2022, the third-largest in OPEC and one of the few OPEC members with meaningful spare crude capacity. In a summit shadowed by Iran, Gaza and Hormuz, that matters. The EIA estimates that oil flows through Hormuz averaged 20 million barrels per day in 2024—roughly 20 percent of global petroleum liquids consumption.
The UAE’s role at Évian said something uncomfortable about the new G7. The old club liked to imagine that shared values were the entry ticket. The new club needs countries that can move oil prices, fund infrastructure and keep Gulf lines open. That is not a moral triumph. It is a risk-management strategy.

...
No. 6: Egypt, the Canal Keeper Insurance Policy
Egypt is the geography policy. It brings neither the wealth of the UAE nor the LNG punch of Qatar, but it has people, position and a canal through which the global economy repeatedly discovers its own fragility. Egypt’s population was about 116.5 million in 2024, and its 2026 economy is projected at roughly $2.57 trillion in purchasing-power terms. The Suez Canal normally handles around 12 to 15 percent of global trade, according to UN Trade and Development, and the Red Sea crisis has shown what happens when that route becomes unsafe: by mid-2024, tonnage through the Suez had fallen by about 70 percent, while Cape of Good Hope arrivals surged 89 percent as ships took longer routes around Africa.
That is why Egypt belongs in the room. It is not a sentimental invite, it is a supply chain invite. In a world of drone wars, shipping shocks, Gaza diplomacy and inflationary choke points, the country that sits on the Suez Canal becomes a kind of global circuit breaker. Egypt, Qatar and the UAE were also present for the Middle East session as the G7 tried to speak to the Iran crisis and wider regional instability. If America becomes less reliable as the organizer of Middle Eastern order, the club needs the people who control the routes, borders and back channels through which disorder travels.
No. 5: Kenya, the African Legitimacy Insurance Policy
Kenya is not the biggest economy on the invitee list. That is precisely why it is interesting. Its value lies in what the G7 otherwise lacks: African legitimacy, institutional convening power and a foothold in the continent where population growth, minerals and climate politics increasingly collide.
The IMF projects Kenya’s 2026 real GDP growth at 4.5 percent and its population at roughly 54.3 million. Nairobi also hosts the only United Nations’ headquarters office in Africa and the Global South, serving as the home base for United Nations Environment Programme and UN-Habitat. Kenya’s government has also identified deposits or occurrences of critical minerals including copper, coltan, rare earth elements, niobium, graphite, lithium, chromium and nickel. That combination—population, institutions, climate diplomacy and minerals—makes Kenya a legitimacy patch for a club that still looks too rich, old and northern. France’s presidency said it was “fully involving” India, Brazil, Kenya and South Korea in the summit process, not seating them at the children’s table.
Kenya’s insurance value is that it helps the G7 speak to Africa without sounding like a creditors’ meeting. In the post-American world, legitimacy is not ornamental. It is infrastructure.
No. 4: Ukraine, the Moral Collateral Insurance Policy
Ukraine is the most obvious invitee and the hardest to rank, as its value is less economic than civilizational. Its 2026 economy is projected at only about $225 billion in nominal GDP and $725 billion in purchasing-power terms. But Ukraine was not at Évian because of GDP; without it, the G7 would look like a homeowners’ association discussing fire safety while the house next door burns.
The G7 has already bound itself to Ukraine financially. In 2024, the U.S. disbursed $20 billion as part of the G7’s $50 billion Extraordinary Revenue Acceleration loan package, designed to be repaid using proceeds from immobilized Russian sovereign assets. Ukraine is also now formally on the European Union accession track; the European Commission says candidate status was granted in June 2022, accession negotiations formally started in June 2024, screening was completed in 2025 and the first accession negotiation cluster was opened in June 2026.
The timing was grim. On June 15, 2026, Russia launched more than 600 drones and 70 missiles at Ukrainian cities, according to Ukrainian officials cited by the Associated Press, killing at least 11 civilians and damaging sites in Kyiv, Kharkiv and Dnipro. Ukraine is the G7’s insurance policy against moral evaporation. If Trump’s Washington wobbles, Europe and its partners need a structure that keeps Russian aggression framed as the central test of democratic credibility, not a regional nuisance to be traded away.
No. 3: South Korea, the Silicon and Shipyards Insurance Policy
South Korea is the most natural almost-member of the G7: rich, democratic, technologically indispensable and permanently parked beside a geopolitical tripwire. Its 2026 economy is projected at about $1.93 trillion in nominal GDP and $3.54 trillion in purchasing-power terms, with a population of roughly 51.6 million.
Its real value is industrial. Samsung and SK Hynix account for almost 70 percent of global DRAM chip production, making South Korea central to the AI, cloud and semiconductor economy the G7 says it wants to secure. It also remains a major shipbuilding power, with industry data putting its 2024 share of global orders below China’s but still around 17 percent of compensated gross tonnage.
This is the insurance policy against Chinese industrial dominance. The G7 can write communiqués about resilient supply chains forever, but without South Korean chips, batteries, shipyards and defense capacity, those communiqués are stationery. France’s decision to include South Korea among the four countries fully integrated into summit preparations is therefore not diplomatic padding. It is an admission that the old G7’s industrial map is obsolete. South Korea is also a reminder that America’s allies are no longer just dependents. Some are load-bearing beams.
No. 2: Brazil, the BRICS and Breadbasket Insurance Policy
Brazil is the insurance policy against the G7 becoming a Western monastery: pious, elegant, irrelevant and increasingly surrounded by unbelievers. It is big enough to matter and
nonaligned enough to be useful. The
IMF’s 2026 estimates put Brazil at about $2.64 trillion in nominal GDP and $5.23 trillion in purchasing power terms, ahead of every G7 economy except the U.S., Germany and Japan on the PPP table. Its population was about 212 million in 2024.
Brazil also feeds the world. Its government reported that agribusiness exports reached $152.6 billion from January to November 2024, accounting for 48.9 percent of the country’s exports; the soybean complex, meats and sugar energy products made up more than 60 percent of that total. The U.S. Department of Agriculture describes Brazil as a major global supplier of soybeans, soybean products, corn, cotton, sugar, coffee, orange juice, meat and ethanol, and as a direct competitor to the U.S. in many of those markets.
Then there is BRICS. Brazil is in a grouping that includes China, India, Russia, South Africa, Egypt, Ethiopia, Indonesia, Iran, Saudi Arabia and the UAE. That makes President Luiz Inácio Lula da Silva awkward company for the G7. It also makes him valuable company. If the G7 wants to avoid ceding the Global South’s operating system to Beijing and Moscow, Brazil is not a guest. It is a router. The old G7 could afford to talk about the Global South. The new G7 has to talk with it. Brazil is the difference between those two sentences.
No. 1: India, the Swing State Superpower Insurance Policy
India was the most important insurance policy at Évian because it is the one country on the list that can change the geometry of the whole system. The numbers are absurd. India’s 2026 nominal GDP is projected at roughly $4.15 trillion, just behind the U.K. and Japan and ahead of France, Italy and Canada; in purchasing-power terms, it is projected at about $18.9 trillion, behind only China and the U.S. The IMF projects India’s 2026 real GDP growth at 6.5 percent and its population at about 1.48 billion.
India has also become a habitual G7 invitee. Indian media had reported that this would be India’s 13th G7 appearance and Prime Minister Narendra Modi’s seventh consecutive participation. Modi framed the trip in exactly the terms that make India indispensable, saying India would “not only speak for itself” but also “give voice to the aspirations of the Global South.”
That is the whole game. India is not merely another large economy. It is the democratic-ish, nationalist, fast-growing, Russia-talking, America-trading, China-competing swing state of the international order. It belongs to BRICS but also to the Quad, alongside the U.S., Japan and Australia. It buys Russian oil but worries about Chinese power. It wants Western technology without Western sermons. It is too big to be lectured and too useful to be ignored. For the G7, India is the hedge against China, demographic decline, Western insularity and an America that may no longer want to lead the system it created. If the post-American world has a kingmaker, it will probably not be Brussels. It may well be New Delhi.
The Charlevoix photograph was a portrait of failed persuasion. The image endured because it captured the end of an illusion: that the democratic world could shame America back into stewardship. Évian was the sequel, and it was colder. Nobody is relying on body language now. They are relying on redundancy. Gas from Qatar, oil capacity from the UAE, the Suez Canal from Egypt, African legitimacy from Kenya, moral clarity from Ukraine, chips and shipyards from South Korea, food and BRICS access from Brazil, scale and swing-state power from India.
The G7 is not abandoning America. It is doing something more delicate and more damning. It is reducing its exposure to America as a single point of failure.
The G7 used to be the place where America organized the West. Now, it may become the place where the West learns to organize itself around America. As Canada’s Prime Minister Mark Carney remarked at Davos this year, “The middle powers must act together, because if we’re not at the table, we’re on the menu.”
View 0 Comments
Submit Correction
View Editorial & AI Guidelines